SSS, PhilHealth and Pag-IBIG Deduction Calculator 2026 (Take-Home Pay)
Quick answer: In 2026 an employee pays 5% of the monthly salary credit to SSS (max ₱1,750), 2.5% of basic salary to PhilHealth (₱250–₱2,500) and 2% to Pag-IBIG (max ₱200). On a ₱25,000 salary that is ₱1,250 + ₱625 + ₱200 = ₱2,075 a month, plus about ₱313.80 withholding tax, for a take-home pay of about ₱22,611.
SSS, PhilHealth and Pag-IBIG Deduction Calculator 2026
Estimate for private-sector employees using 2026 SSS (5% employee share of MSC), PhilHealth (2.5%, ₱10,000–₱100,000), Pag-IBIG (2%, max ₱200) and the BIR withholding tax table effective 2023 onward. Allowances, overtime, de minimis benefits and loans are not included.
Take-Home Pay Table 2026 (Monthly)
| Basic salary | SSS | PhilHealth | Pag-IBIG | Withholding tax | Take-home pay |
|---|---|---|---|---|---|
| ₱12,000 | ₱600.00 | ₱300.00 | ₱200.00 | ₱0.00 | ₱10,900.00 |
| ₱15,000 | ₱750.00 | ₱375.00 | ₱200.00 | ₱0.00 | ₱13,675.00 |
| ₱18,000 | ₱900.00 | ₱450.00 | ₱200.00 | ₱0.00 | ₱16,450.00 |
| ₱20,000 | ₱1,000.00 | ₱500.00 | ₱200.00 | ₱0.00 | ₱18,300.00 |
| ₱25,000 | ₱1,250.00 | ₱625.00 | ₱200.00 | ₱313.80 | ₱22,611.20 |
| ₱30,000 | ₱1,500.00 | ₱750.00 | ₱200.00 | ₱1,007.55 | ₱26,542.45 |
| ₱35,000 | ₱1,750.00 | ₱875.00 | ₱200.00 | ₱1,701.30 | ₱30,473.70 |
| ₱40,000 | ₱1,750.00 | ₱1,000.00 | ₱200.00 | ₱2,618.40 | ₱34,431.60 |
| ₱50,000 | ₱1,750.00 | ₱1,250.00 | ₱200.00 | ₱4,568.40 | ₱42,231.60 |
| ₱60,000 | ₱1,750.00 | ₱1,500.00 | ₱200.00 | ₱6,518.40 | ₱50,031.60 |
| ₱80,000 | ₱1,750.00 | ₱2,000.00 | ₱200.00 | ₱10,887.55 | ₱65,162.45 |
| ₱100,000 | ₱1,750.00 | ₱2,500.00 | ₱200.00 | ₱15,762.55 | ₱79,787.45 |
Amounts are employee shares only, before allowances, overtime, loans and other deductions. Find your exact SSS bracket in the SSS monthly salary credit (MSC) table.
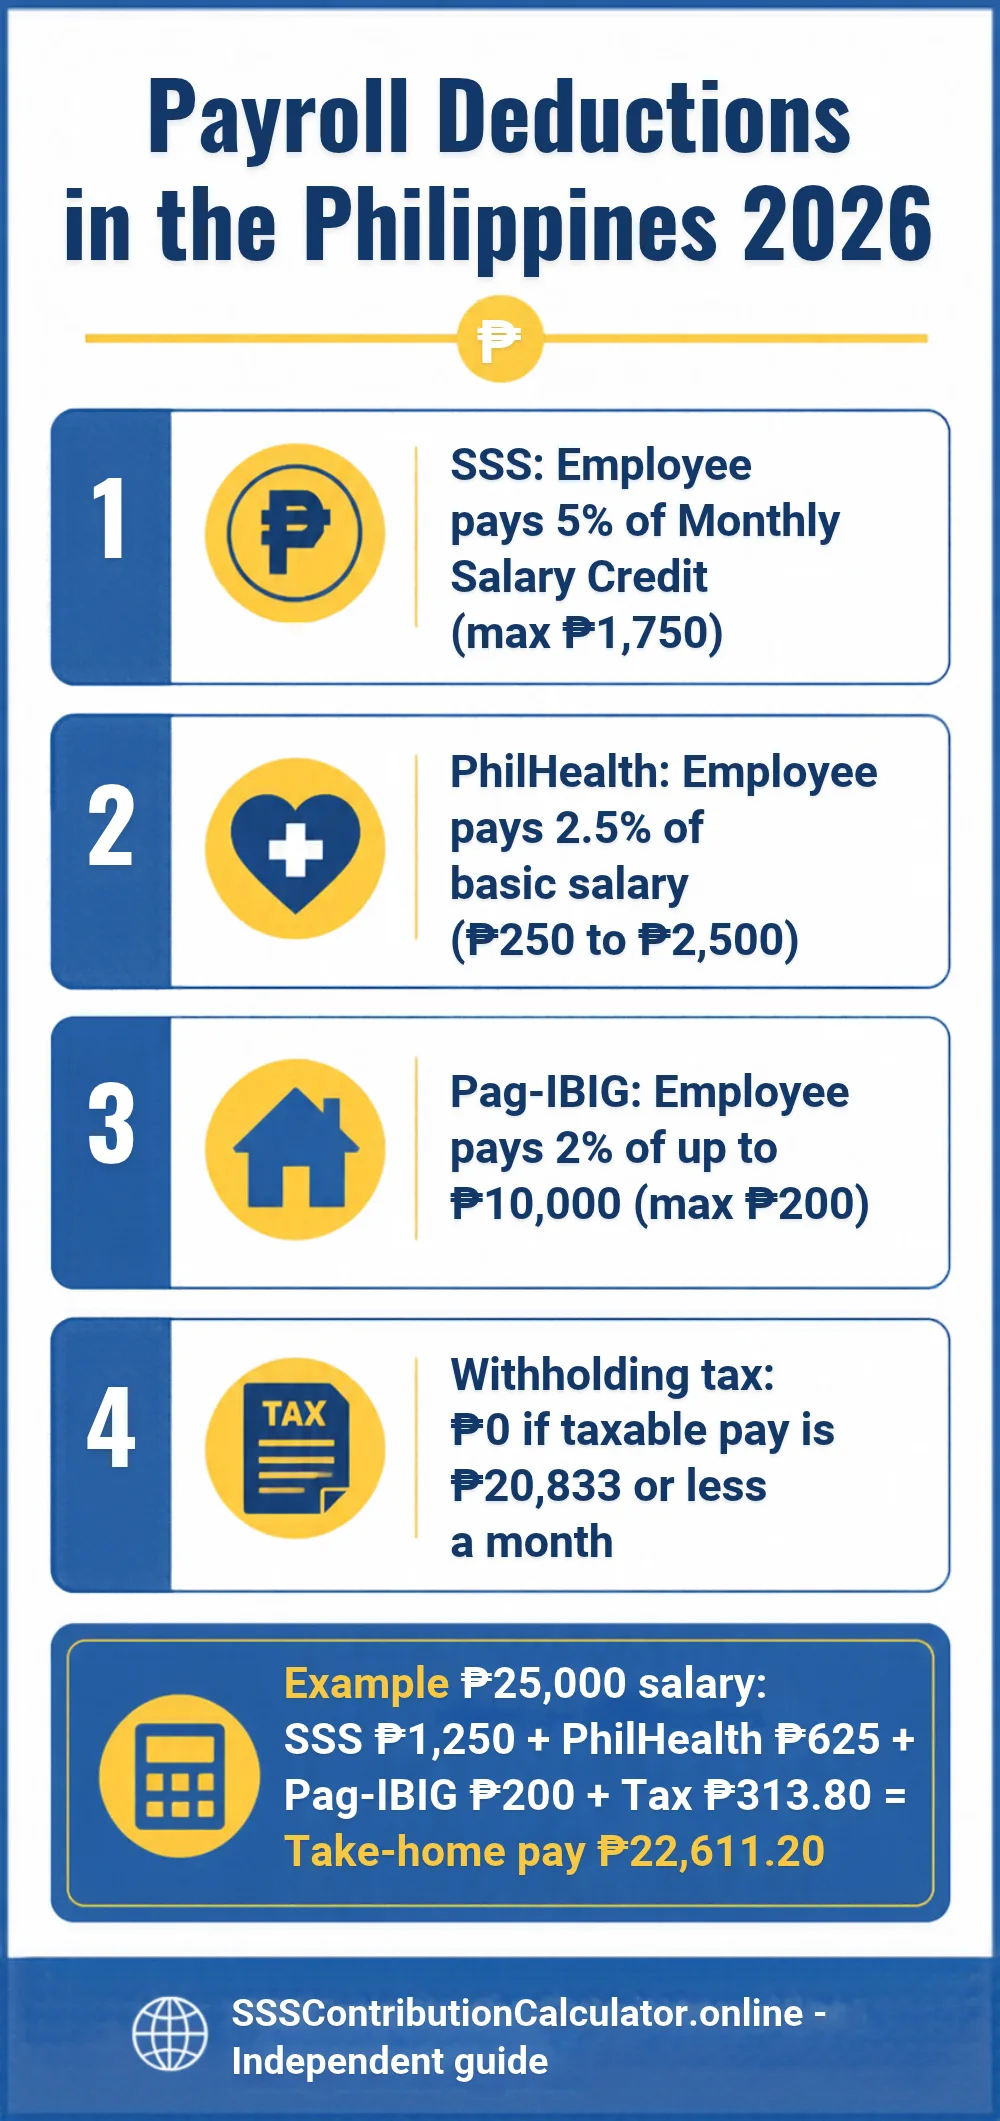
How Each Deduction Is Computed
| Deduction | Employee share | Employer share | Salary limits |
|---|---|---|---|
| SSS | 5% of MSC | 10% of MSC + EC ₱10/₱30 | MSC ₱5,000–₱35,000 |
| PhilHealth | 2.5% of basic salary | 2.5% | Floor ₱10,000, ceiling ₱100,000 |
| Pag-IBIG (HDMF) | 2% (1% if ₱1,500 or less) | 2% | Up to ₱10,000 fund salary |
| Withholding tax | Per BIR table on taxable pay | — | Tax-free up to ₱20,833/month |
- SSS: round your salary to its MSC bracket, then multiply by 5%. Details on the SSS contribution table 2026, or compute it on the SSS contribution calculator 2026.
- PhilHealth: 5% total premium split 50/50. See the PhilHealth contribution calculator.
- Pag-IBIG: 2% of salary up to ₱10,000. See the Pag-IBIG contribution calculator.
- Withholding tax: salary minus the three contributions, then apply the BIR table below.
BIR Withholding Tax Table 2026 (Monthly)
| Monthly taxable compensation | Withholding tax |
|---|---|
| ₱20,833 and below | ₱0 |
| ₱20,833 – ₱33,332 | 15% of the excess over ₱20,833 |
| ₱33,333 – ₱66,666 | ₱1,875 + 20% of the excess over ₱33,333 |
| ₱66,667 – ₱166,666 | ₱8,541.80 + 25% of the excess over ₱66,667 |
| ₱166,667 – ₱666,666 | ₱33,541.80 + 30% of the excess over ₱166,667 |
| ₱666,667 and above | ₱183,541.80 + 35% of the excess over ₱666,667 |
This TRAIN Law table has applied since January 1, 2023. The 13th-month pay and other benefits up to ₱90,000 a year are tax-exempt.
Example: ₱30,000 Monthly Salary
- SSS: MSC ₱30,000 × 5% = ₱1,500
- PhilHealth: ₱30,000 × 2.5% = ₱750
- Pag-IBIG: ₱10,000 × 2% = ₱200
- Taxable pay: ₱30,000 − ₱2,450 = ₱27,550 → tax = (₱27,550 − ₱20,833) × 15% = ₱1,007.55
- Take-home pay: ₱26,542.45 a month (₱13,271.23 per cut-off)
Self-Employed, Voluntary and OFW Members
Without an employer, you pay both shares: 15% to SSS, the full 5% PhilHealth premium and your Pag-IBIG contribution. See SSS for self-employed, voluntary members and OFWs.
Also useful: Getting a year-end bonus? Compute it with the 13th month pay calculator 2026 — it is tax-free up to ₱90,000.
FAQs
How much is the SSS, PhilHealth and Pag-IBIG deduction in 2026?
For an employee, SSS is 5% of the monthly salary credit (up to ₱1,750), PhilHealth is 2.5% of basic salary (₱250 to ₱2,500), and Pag-IBIG is 2% of up to ₱10,000 (maximum ₱200). On a ₱20,000 salary that is ₱1,000 + ₱500 + ₱200 = ₱1,700 a month.
How many percent is the SSS deduction from salary?
The employee pays 5% of the monthly salary credit (MSC) and the employer pays 10% plus the EC premium, for a total of 15%. The MSC is capped at ₱35,000, so the employee share is at most ₱1,750 a month.
Are government contributions deducted before tax?
Yes. Mandatory employee shares for SSS, PhilHealth and Pag-IBIG are excluded from taxable compensation, so withholding tax is computed on salary minus these contributions.
Is there withholding tax on a ₱20,000 salary?
No. After SSS, PhilHealth and Pag-IBIG, taxable pay on ₱20,000 is ₱18,300, below the ₱20,833 monthly tax-exempt threshold.
Are contributions deducted every cut-off?
Many employers split the monthly contributions across the two cut-offs; others deduct them once a month. The monthly total is the same.
Related guides and tools
- SSS Contribution Calculator 2026
- SSS Monthly Salary Credit (MSC) Table
- PhilHealth Contribution 2026
- Pag-IBIG Contribution 2026
- SSS Contribution Table 2026 PDF
Independent guide, not affiliated with SSS, PhilHealth, Pag-IBIG or BIR. Estimates only; your payslip may differ because of allowances, absences, loans and employer payroll practice.